September has earned its reputation as one of the more difficult months for markets, and this year is doing its part to live up to it. Between a Fed meeting that’s carrying more weight than it has in a while and a geopolitical backdrop that hasn’t let up, there’s a lot to sort through this month.
The Fed begins its two-day meeting today, which will culminate in an interest rate decision. At the beginning of the year, most investors would have likely bet on greater chances of a rate decrease over a rate increase. Now, however, the narrative has changed. In fact, the FedWatch tool from the CME Group has the likelihood of a rate increase up to a 92% chance.
The war in Iran has extended far past initial timeline estimates, keeping oil prices higher for longer and impacting energy costs. Inflation has stayed hotter than expected, and the jobs market has been strong. These points, paired with a more hawkish Fed Chair in Kevin Warsh, have ultimately flipped the narrative from rate cuts to rate hikes.
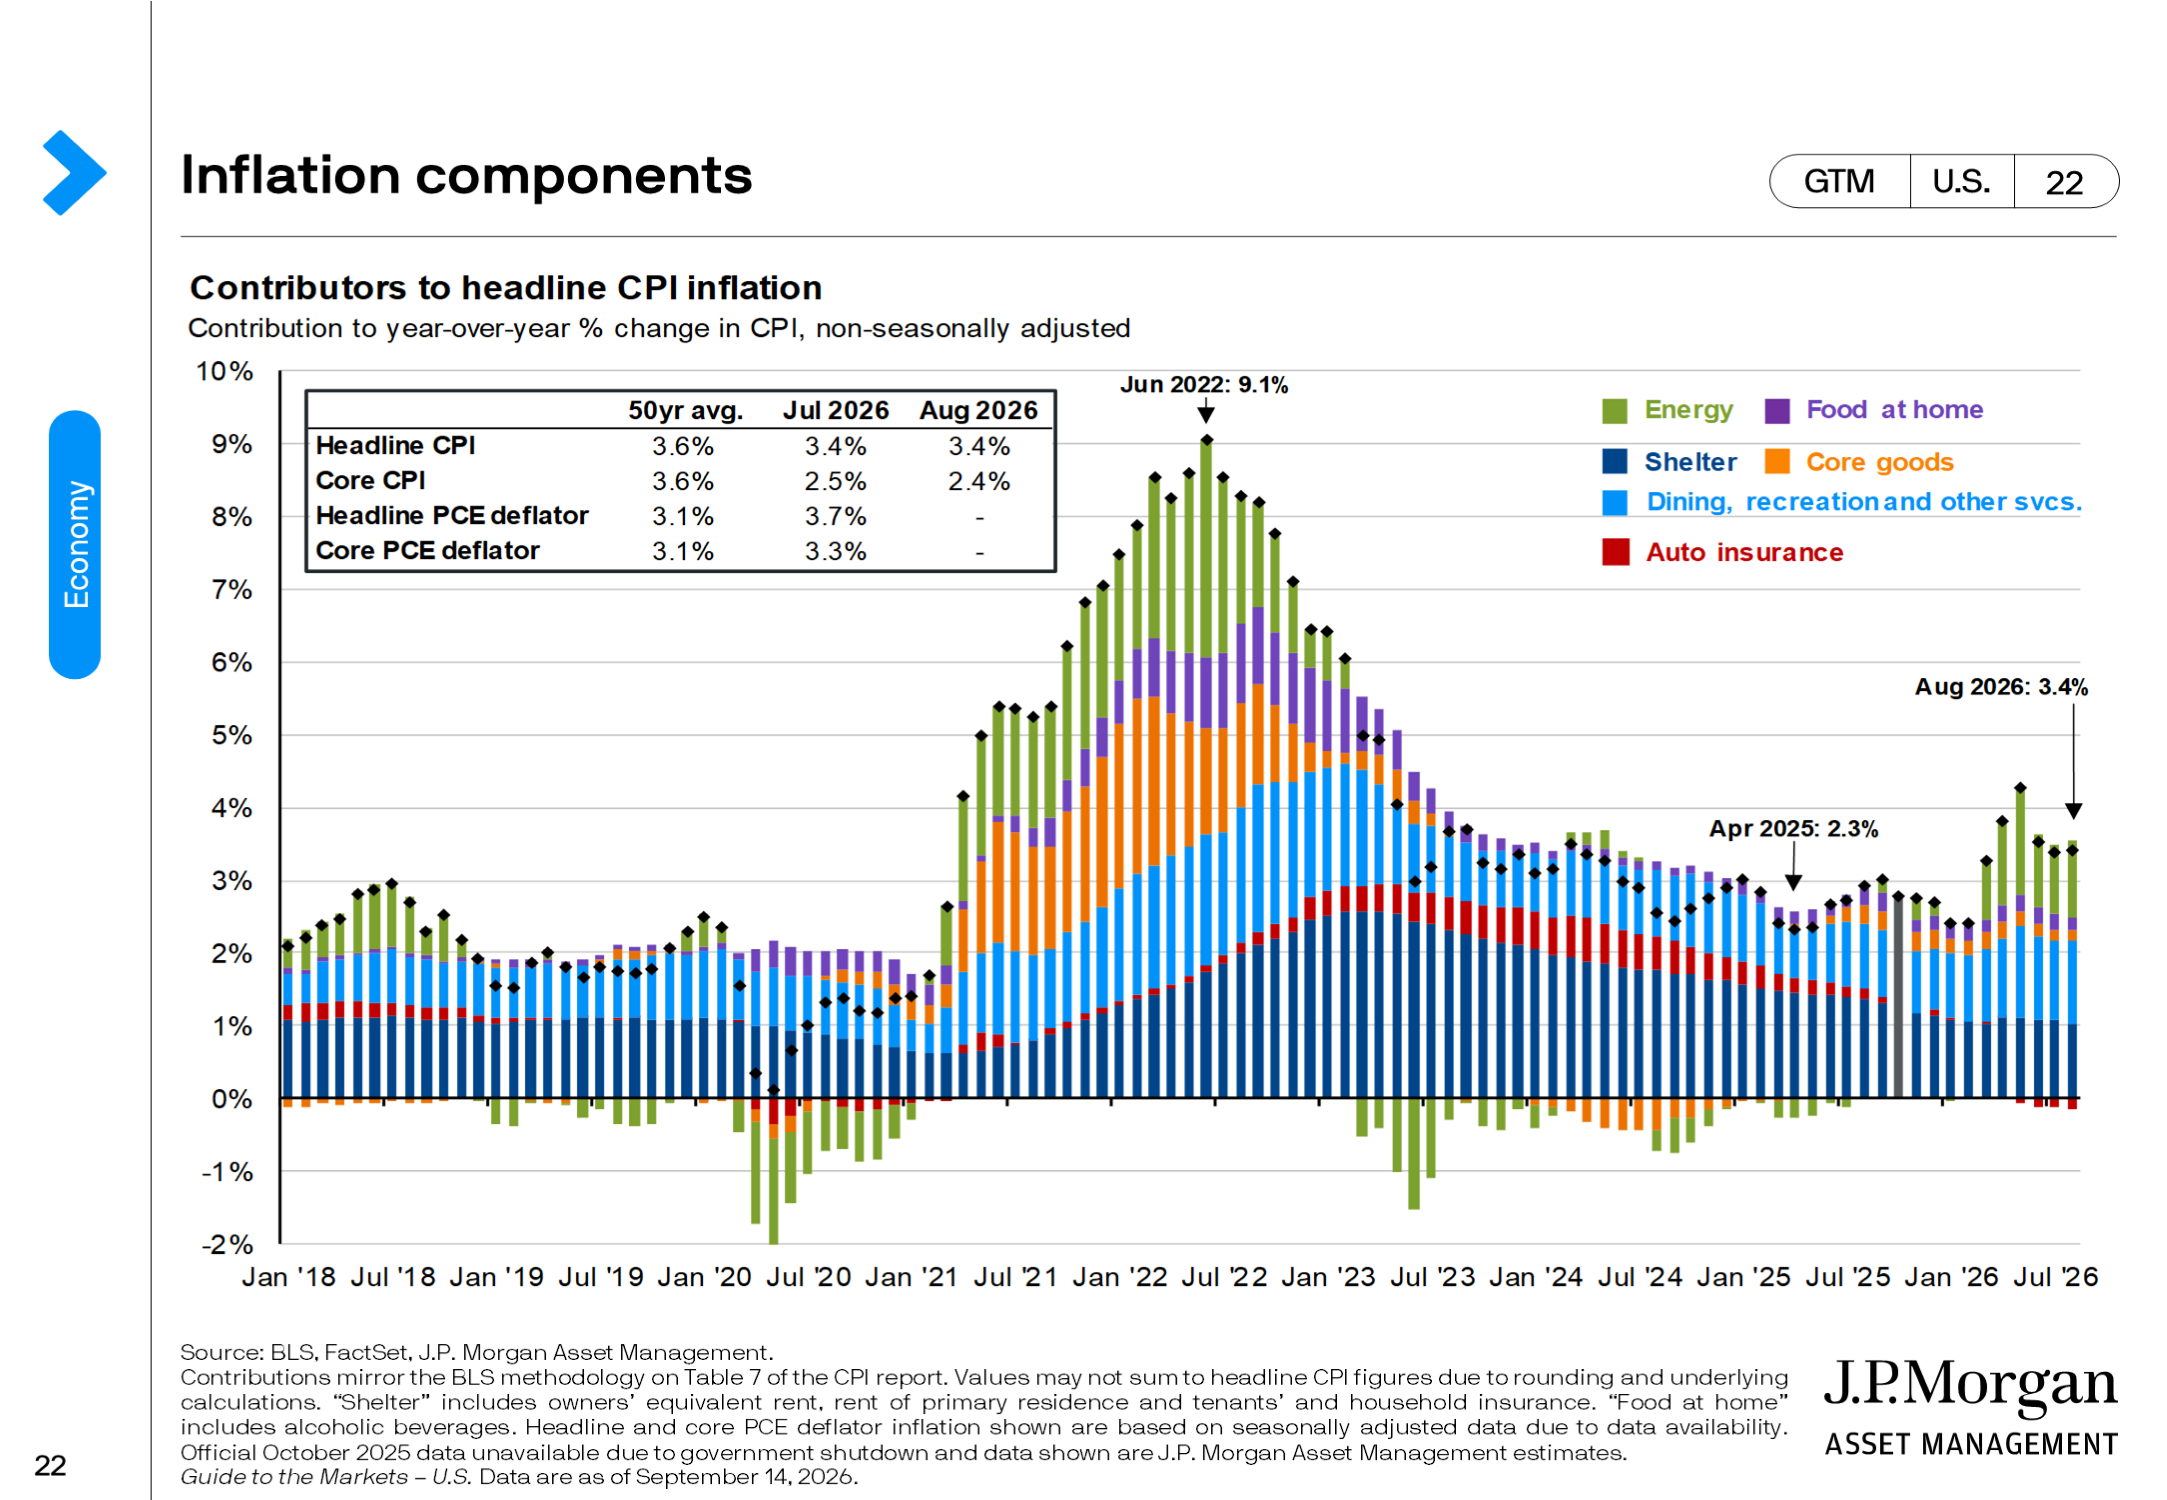
Energy costs continue to be the primary culprit for higher inflation today compared to one year ago. These higher costs have led to the hot inflation, which in turn pushes the Fed towards a more conservative stance on interest rates. All these points are working in tandem.
Treasury yields have been the clearest market reaction to this shift. The 10-year yield has climbed to a high of 5.04%, a level we haven’t seen since 2007, and the move has been fairly swift given how quickly the rate-hike probability has built over the past several weeks. As yields rise, bond prices move the opposite direction, which has weighed on bond returns this year despite a still-respectable coupon. I wrote in the August Viewpoints about how price movement, not coupon income, has been driving the bulk of bond returns in this environment, and September has been another example of that same dynamic at work.
None of this changes how we’re thinking about client portfolios. This kind of shift is exactly why we build fixed income allocations around duration and rate sensitivity – we want bonds to behave like bonds. Lower risk and lower volatility. It’s also a reminder that a hawkish turn from the Fed doesn’t automatically mean trouble for equities, which have shown resilience through plenty of rate uncertainty before. Where the Fed ultimately lands this week, and what it signals for the months after, remain to be seen. As we so often say, today’s headlines and tomorrow’s reality are seldom the same.
IMPORTANT DISCLOSURE INFORMATION: Please remember that past performance is no guarantee of future results. Different types of investments involve varying degrees of risk, and there can be no assurance that the future performance of any specific investment, investment strategy, or product (including the investments and/or investment strategies recommended or undertaken by PDS Planning, Inc. [“PDS”]), or any non-investment related content, made reference to directly or indirectly in this blog will be profitable, equal any corresponding indicated historical performance level(s), be suitable for your portfolio or individual situation, or prove successful. Due to various factors, including changing market conditions and/or applicable laws, the content may no longer be reflective of current opinions or positions. Moreover, you should not assume that any discussion or information contained in this blog serves as the receipt of, or as a substitute for, personalized investment advice from PDS. To the extent that a reader has any questions regarding the applicability of any specific issue discussed above to his/her individual situation, he/she is encouraged to consult with the professional advisor of his/her choosing. PDS is neither a law firm nor a certified public accounting firm and no portion of the blog content should be construed as legal or accounting advice. A copy of the PDS’ current written disclosure Brochure discussing our advisory services and fees is available for review upon request or at www.pdsplanning.com. Please Note: PDS does not make any representations or warranties as to the accuracy, timeliness, suitability, completeness, or relevance of any information prepared by any unaffiliated third party, whether linked to PDS’ web site or blog or incorporated herein, and takes no responsibility for any such content. All such information is provided solely for convenience purposes only and all users thereof should be guided accordingly. Please Remember: If you are a PDS client, please contact PDS, in writing, if there are any changes in your personal/financial situation or investment objectives for the purpose of reviewing/evaluating/revising our previous recommendations and/or services, or if you would like to impose, add, or to modify any reasonable restrictions to our investment advisory services. Unless, and until, you notify us, in writing, to the contrary, we shall continue to provide services as we do currently. Please Also Remember to advise us if you have not been receiving account statements (at least quarterly) from the account custodian.